


How to Set Up a Company in Spain: Steps, Costs and Taxes
Setting up a company in Spain means choosing the right legal form and completing the identification, notarial, registry and tax formalities that apply to the founders and activity. This guide explains the general route for a Spanish capital company; it does not replace legal, tax, immigration or Social Security advice for a specific case.
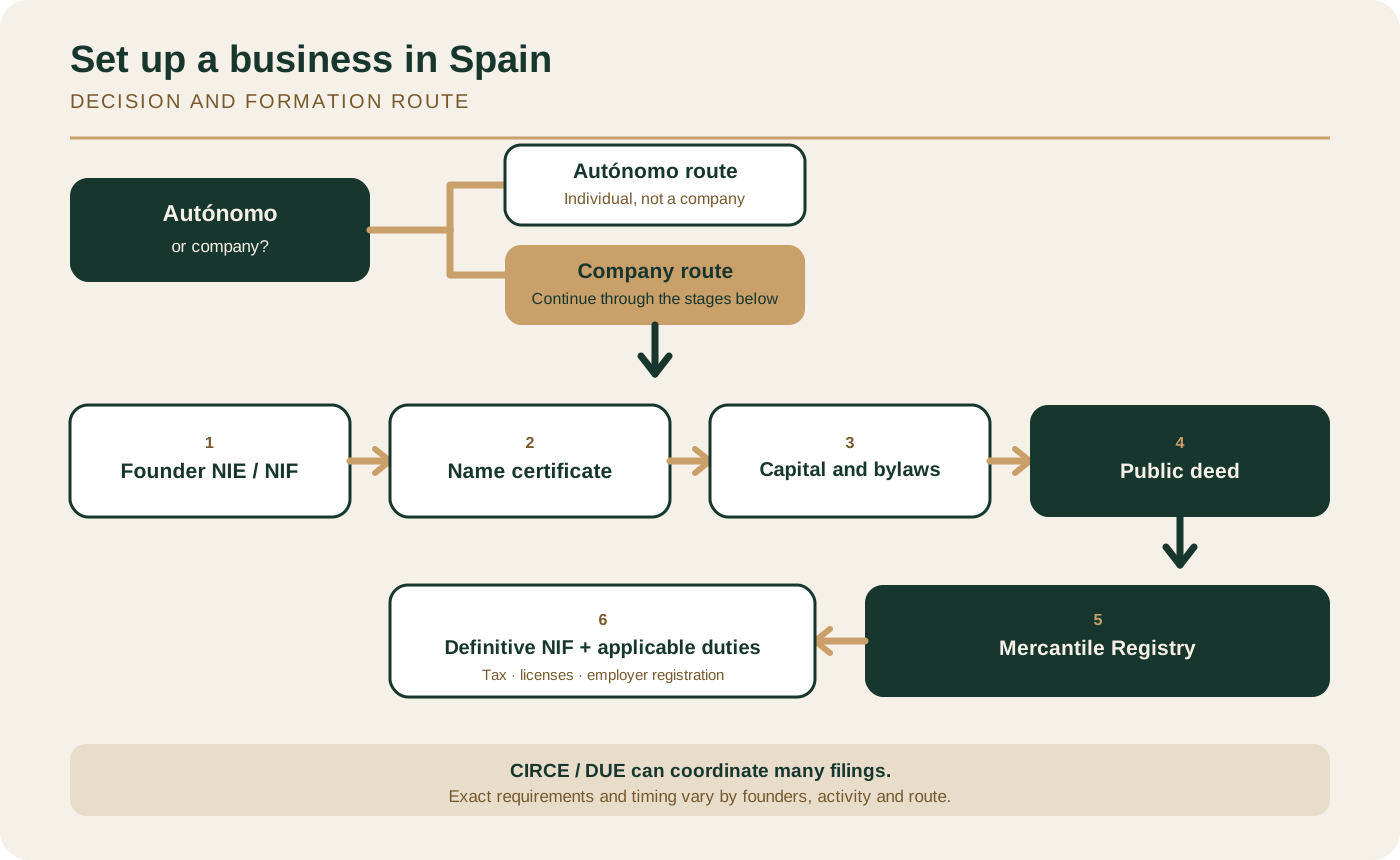
Short answer. A Spanish capital company is formed by choosing the legal form, clearing the company name, documenting the capital, signing a public deed and registering the company with the competent Mercantile Registry. Foreign shareholders and directors generally need a Spanish NIE or NIF, but owning shares does not by itself create a universal residence-permit requirement. For an S.L., the statutory minimum capital is €1; additional safeguards apply while capital and the legal reserve remain below €3,000. Electronic systems can coordinate many filings, but the exact route, documents and total time depend on the founders, activity and registration channel.
Register a Company in Spain Online
Contents
- Choose a business structure
- Company formation steps
- Foreign founders
- Costs
- Taxes and post-registration duties
- Branch versus subsidiary
- Frequently asked questions
Choose a business structure
The legal form determines whether the business has separate legal personality, how liability works and which capital and governance rules apply.
| Route | Legal position | Capital baseline | Practical boundary |
|---|---|---|---|
| Autónomo | An individual carries on the activity personally; this is not a company. | No company share capital. | Registration, personal tax and Social Security follow the self-employed route. |
| Sociedad Limitada (S.L.) | A separate capital company after registration. | €1 statutory minimum, with additional safeguards while capital and the legal reserve remain below €3,000. | Commonly considered for closely held small and medium-sized businesses; governance and transfer rules still require case-specific review. |
| Sociedad Anónima (S.A.) | A separate capital company after registration. | €60,000; every share must be fully subscribed and at least one quarter of each share’s nominal value paid when the deed is executed. | Designed for structures requiring a larger capital base or more open share ownership. |
| Branch | Part of the foreign parent, without separate legal personality. | No general company-capital minimum for the branch itself. | The parent remains liable for branch obligations. |
| Subsidiary | A Spanish company with its own legal personality after registration. | The capital rules of its selected form, usually S.L. or S.A. | Its deed, registration, governance and tax duties follow that form. |
The Capital Companies Act is the primary legal reference for S.L. and S.A. capital and incorporation rules. Choosing between an autónomo route and a company requires a liability, tax, governance and Social Security assessment—not just a comparison of starting capital.
How company formation in Spain works
- Choose the legal form and company design. Identify the founders, director or directors, registered office, activity and ownership structure.
- Obtain the necessary founder identifiers. Foreign individual shareholders and directors generally need an NIE; a foreign legal entity needs a Spanish NIF.
- Clear the company name. Request the negative company-name certificate from the Central Mercantile Registry and follow the current RMC form rather than relying on a fixed number of alternatives.
- Define the capital contribution and prepare the bylaws. Record cash or non-cash contributions and set the company’s governance rules.
- Execute the public deed before a notary. The deed incorporates the agreed company terms and identifies the founders, contributions and governing body.
- Obtain or regularize the company NIF and register the deed. The company uses an NIF requested through Modelo 036. Register the deed with the competent territorial Mercantile Registry.
- Complete the registrations that apply to the business. These may include census and activity data, tax registrations, municipal or regulated-activity licenses, and employer registration before hiring workers.
CIRCE and the Documento Único Electrónico (DUE) can coordinate many of these formalities, but electronic processing does not make every case appointment-free or remove the notarial and registry stages. CIRCE’s published processing range is not a promise of total elapsed time.
Capital contributions and bank evidence
Cash contributions are normally evidenced through a credit-institution deposit certificate or delivery to the notary. For an S.L., the founders may instead state in the deed that they are jointly liable to the company and its creditors for the reality of the cash contributions. A bank or a particular service provider may still require an account for its own process. This legal alternative is set out in article 62 of the Capital Companies Act.
NIF and legal personality
A capital company must be incorporated by public deed and entered in the competent Mercantile Registry. On registration, it acquires the legal personality corresponding to its selected type. The company uses an NIF requested through Modelo 036. The Tax Agency’s legal-entity NIF guidance explains provisional and definitive status when documentation is still being completed.
Looking up a Spanish company register entry
The Central Mercantile Registry handles company-name functions, while territorial Mercantile Registries record incorporated companies and later corporate acts. For current registry information, use the official Central Mercantile Registry and Registradores de España channels. This article explains formation; it is not a company-search database.
What foreign founders need to know
Foreign individuals who become shareholders or directors generally need an NIE; foreign legal entities need a Spanish NIF. The NIE is an identifier, not a residence or work permit. Residence and Social Security consequences depend on what the person will do, whether the director is remunerated and the person’s immigration status. See the NIE requirements guide for the identification stage, then verify the current official route for the individual case.
A company acts through its statutory representative or director. Separate tax-representation duties for non-residents arise only in specified cases, including certain non-EU taxpayers operating through a permanent establishment, particular non-established IVA situations, or when the Tax Agency requires representation. A voluntary power of attorney may be used for assistance, but it is not the same as a universal legal requirement. The Tax Agency’s representation guidance sets out the relevant categories.
For readers who want assistance rather than a general legal overview, the company incorporation service is the separate commercial route. Its scope, documents and delivery terms belong on that service page.
What does it cost to set up a company in Spain?
There is no responsible single total for every company. Build a case-specific budget from these components:
| Cost factor | What it covers |
|---|---|
| Share capital | Funding subscribed to the company under the rules of the selected legal form. |
| Company-name certificate | The current RMC application and certification route. |
| Notary | Execution of the public deed and any related copies or instruments. |
| Mercantile Registry | Registration of the deed and any required registry publication or certification. |
| Foreign-document preparation | Sworn translation, legalization or apostille where required. |
| Power of attorney | Notarial, translation and legalization costs if the founders choose representation. |
| Licenses and permits | Municipal or regulated-activity requirements for the actual business. |
| Professional or service fees | Legal, tax, accounting or incorporation assistance selected by the founders. |
Share capital is company funding, not a government fee. The total depends on the legal form, documents, activity and route. Obtain current quotes before publishing or promising a total.
Taxes and post-registration duties
2026 corporate tax and IVA snapshot
For tax periods beginning in 2026, the Tax Agency corporate-tax table lists a 25% general corporate-tax rate; for micro-enterprises with net turnover below €1 million, 19% on the first €50,000 of taxable base and 21% on the remainder; 23% for qualifying small entities under article 101 LIS; and 15% for qualifying newly created entities. Classification and eligibility matter, so 25% and 15% are not universal rates.
The general IVA rate is 21%. The Tax Agency IVA table also lists reduced rates of 10% and 4%, and a 0% rate for certain operations. The applicable treatment depends on the transaction, exemptions and place-of-supply rules. For ongoing bookkeeping, payroll and filing support, see accounting services in Spain.
Tax rates and administrative guidance can change. Recheck the current Tax Agency pages before relying on a year-specific rate.
Post-registration checklist
- Confirm the company’s definitive NIF and census and activity data.
- Obtain the municipal or regulated-activity permits that apply.
- Set up compliant invoicing, bookkeeping and tax records.
- Maintain beneficial-ownership information and corporate books where applicable.
- Prepare annual accounts and required Mercantile Registry filings.
- Register as an employer before hiring workers for the first time.
Before hiring
An employer that will hire workers for the first time must register as a company with Social Security before the activity involving those workers begins and obtain its principal contribution account code through the TA.6 route. Whether a shareholder or director belongs in RETA or another regime depends on ownership, control, duties and remuneration; it is not one universal rule. The Social Security employer-registration page provides the current route.
Before work starts, check employee affiliation and registration, payroll setup, the applicable collective agreement and occupational requirements. Employment classification and contributions are case-specific, so obtain professional advice instead of applying a generic percentage.
Branch versus subsidiary
A branch is part of the foreign parent and does not have separate legal personality; the parent’s liability extends to branch obligations. A subsidiary is a Spanish legal entity, commonly an S.L. or S.A., and follows the corresponding capital, deed, registration and tax rules. The correct choice depends on liability, governance, tax and reporting considerations.
The ICEX guide to setting up a business in Spain provides an official overview. Neither route is categorically better or cheaper for every group.
Incorporate a Spanish Company Online
Official sources
- Consolidated Capital Companies Act — BOE
- CIRCE and DUE — official PAE portal
- Setting up a business in Spain — ICEX Invest in Spain
- Legal-entity NIF — Spanish Tax Agency
- Corporate-tax rates — Spanish Tax Agency
- IVA rates — Spanish Tax Agency
- Employer registration — Spanish Social Security
Frequently asked questions
Can a non-resident set up a company in Spain without moving there?
Foreign individuals and legal entities may be shareholders or directors after obtaining the applicable Spanish NIE or NIF. This does not guarantee that every case can be completed remotely: immigration and Social Security consequences depend on the person’s duties, remuneration and status.
What is the minimum capital for a Spanish S.L.?
The statutory minimum is €1. While capital and the legal reserve remain below €3,000, at least 20% of annual profit must go to the legal reserve until that threshold is reached. If the company is liquidated without enough assets, shareholders are jointly liable for the difference between €3,000 and the subscribed capital.
Do I need a Spanish bank account to incorporate an S.L.?
Not as a universal legal rule. Cash contributions are normally evidenced by a credit-institution deposit certificate or delivery to the notary. For an S.L., the founders may instead state in the deed that they are jointly liable for the reality of those contributions. A bank or service process may still require an account.
How long does company formation in Spain take?
There is no reliable universal total. CIRCE describes a 1–10-day processing range for coordinated formalities, depending on the use of standardized documents, but founder identifiers, name clearance, the notarial appointment, registry review, foreign documents and activity licenses can extend the elapsed time.
What taxes does a Spanish company pay?
For tax periods beginning in 2026, the official table includes a 25% general corporate-tax rate, separate 19% and 21% bands for micro-enterprises, 23% for qualifying small entities and 15% for qualifying newly created entities. IVA may apply at 21%, 10%, 4% or, for certain operations, 0%. Classification, the taxable base and the transaction determine the result.
Must every non-resident founder appoint a legal or fiscal representative?
No. A company acts through its statutory representative or director. Separate tax-representation duties arise only in specified non-resident cases or when required by the Tax Agency. A founder may grant a voluntary power of attorney for assistance, but that is not a universal requirement.