


Moving from Employee/A1 to Self-Employed on Spain’s DNV
If you already hold Spain’s international-teleworker residence authorization and replace foreign employment with genuine self-employment, treat the move as four connected but separate procedures. You must address the basis of your authorization with the Large Companies and Strategic Groups Unit (UGE), obtain a new decision on the social-security legislation that applies, complete the Spanish tax-census step with AEAT, and register in RETA if Spanish social-security law applies.
An A1 or certificate of coverage proves which country’s social-security legislation applies. It does not grant your Spanish immigration status, register your business with AEAT or, by itself, settle whether RETA is required. An employee A1 is not automatically invalid merely because your circumstances change. However, it does not prove the changed self-employed facts and should be reported to the issuing institution and redetermined. Under EU rules, an issued document remains binding until the issuing state withdraws it or declares it invalid, while that institution must reconsider the basis if the facts are questioned (Regulation 987/2009, Article 5).
For the wider entry requirements, see Spain Digital Nomad Visa requirements. If you do not yet hold the authorization, use the separate guide on how to apply for Spain’s Digital Nomad Visa.
TL;DR
The four systems answer different questions
| System | Question it answers | Authority or institution | What it does not decide |
|---|---|---|---|
| International-teleworker authorization | Does the new professional relationship still satisfy the conditions of the Spanish residence authorization? | UGE | Which country’s social-security law applies, tax registration or RETA by itself |
| Applicable social security and A1 | Which country’s legislation covers the real work pattern? | Competent social-security institution or institutions | Immigration permission, Spanish tax registration or tax residence |
| Spanish tax census | Must the person register or amend business details, and from what activity date? | AEAT, using current Form 036 where required | DNV approval or the applicable social-security country |
| Spanish self-employed Social Security | Must the person register in RETA, and from what date? | TGSS/Importass, if Spanish legislation applies | UGE acceptance or AEAT tax treatment |
EU coordination normally subjects a person to one member state’s social-security legislation. The default is the law of the country where the employed or self-employed activity is actually pursued, subject to posting and multi-state rules (Regulation 883/2004, Articles 11–13). A foreign employer or client does not, on its own, mean the work is pursued outside Spain.
Before, trigger and after: what changes
| Layer | Before | Trigger to record | After the trigger | Evidence to retain |
|---|---|---|---|---|
| UGE immigration | Authorization rests on foreign employment and its supporting evidence | Employment ends or the qualifying relationship changes | Communicate the material change within 30 days and prove the new professional basis | Current authorization, cessation evidence, professional contracts and remote-work terms |
| Social security/A1 | Employee coverage is evidenced under a particular legal route and fact pattern | Employment or work pattern changes | Ask the competent institution to redetermine applicable legislation | Old A1, change date, physical work locations, new contracts and the new decision/certificate |
| AEAT | No self-employed activity is recorded, or existing census facts describe another activity | Business activity or operations are to begin | File or amend Form 036 before starting where required | Filed Form 036 and the effective activity details |
| RETA | Employee regime or valid foreign coverage applies | Spain is determined to be the competent social-security state for self-employment | Request RETA registration before activity starts | Applicable-legislation decision and RETA registration record |
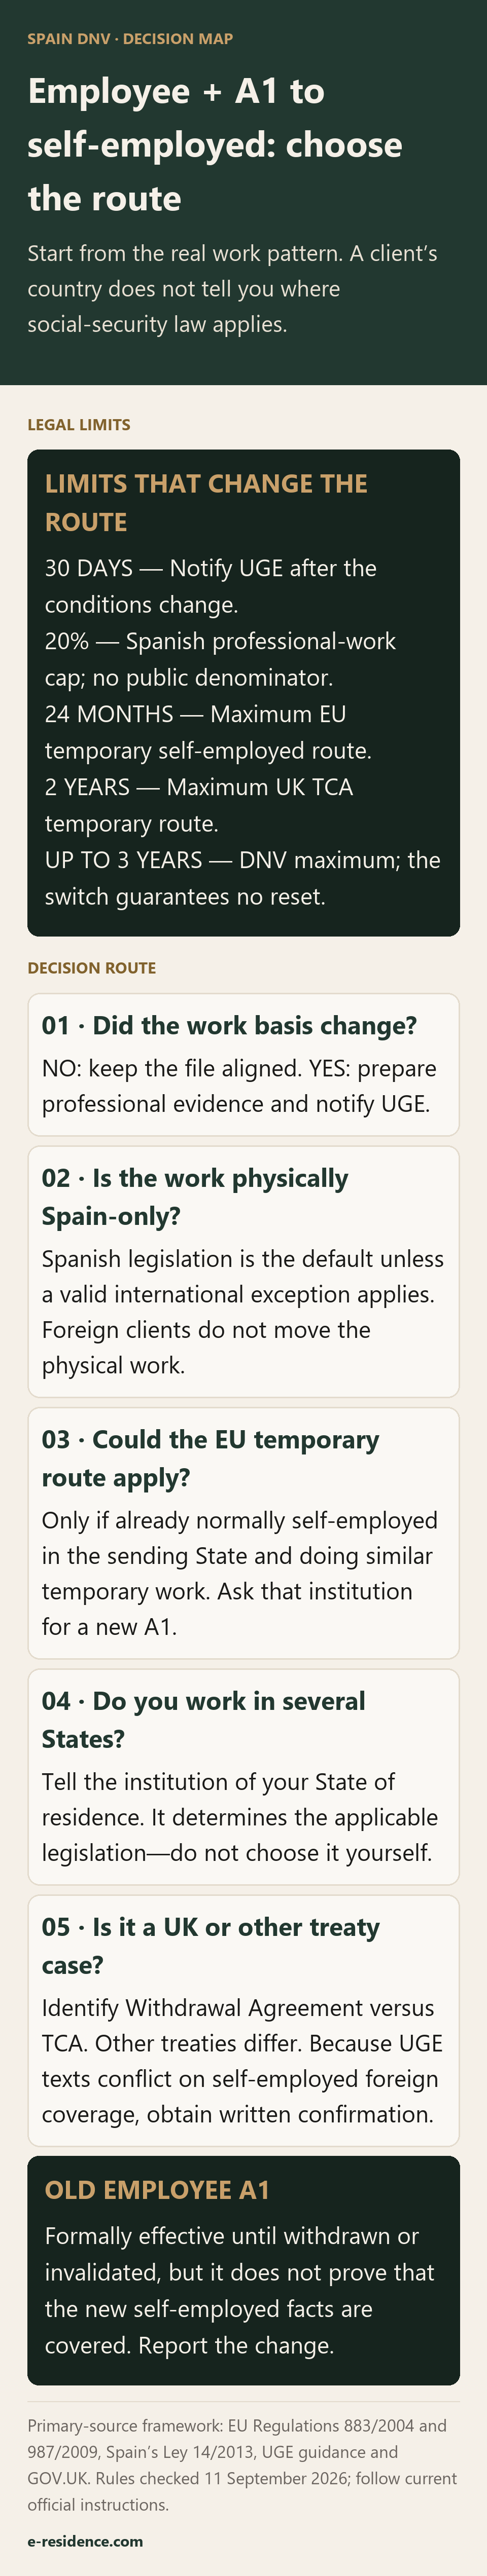
The dates may not be identical. Record the employment end date, the date the commercial relationship exists, and the date activity or operations actually begin. The 30-day UGE clock follows the change affecting the authorization conditions; it is not a general 30-day period before and after the end of employment.
Decision tree: choose the route from the facts
-
Will foreign employment and its facts covered by the employee A1 continue unchanged? If yes, there may be no employee-to-self-employed transition yet. Do not create invoices or sign professional work as though it were covered without checking both UGE and the A1 issuer.
-
Has employment ended, but independent activity has not begun? Use this planning interval to confirm the UGE submission route, present the future work pattern to the competent social-security institution and prepare AEAT/RETA filings. Do not assume that a gap automatically extends either the old immigration basis or the employee A1.
-
Will all self-employed work be physically performed from Spain? The EU default points to Spanish legislation unless a specific coordination exception applies. If Spain applies, align the required AEAT and RETA starts before activity. Importass states that RETA registration must be requested before starting and can be prepared in advance (Importass).
-
Were you already normally self-employed in another EU/EEA/Swiss state and is the activity in Spain temporary and similar? A self-employed temporary-work route may preserve the first state’s legislation, but it has different conditions from employee posting. EU law requires genuine prior normal self-employment there, a similar activity in Spain, continued capacity to resume the activity in the first state, and an anticipated period not exceeding 24 months (Regulation 883/2004, Article 12; Regulation 987/2009, Article 14). Obtain a new certificate matching the self-employed facts rather than relying on the employee A1.
-
Will you combine employment and self-employment, or work in two or more countries? Stop and obtain an institutional determination. The special EU rule for employment in one state and self-employment in another applies only when the activities are genuinely pursued in different states—not merely when counterparties are abroad. A person working in two or more member states must inform the designated institution in the state of residence (Regulation 987/2009, Article 16). Separately ask UGE to confirm that the proposed mix fits the authorization; UGE’s current holder guidance does not state that every employment-plus-freelance combination is compatible with the authorization.
-
Is the case connected to the UK? First determine whether the Withdrawal Agreement protects the person’s pre-2021 position. Otherwise, the UK–EU Trade and Cooperation Agreement Protocol applies; it is similar to, but not identical with, EU coordination (European Commission). HMRC has a certificate route for qualifying similar self-employed activity carried out temporarily in an EU country for up to two years, but HMRC must decide whether the facts qualify (GOV.UK).
-
Is the origin country outside the EU/EEA/Switzerland and the UK? Check whether an agreement with Spain applies, then read that treaty’s personal, activity and duration rules. Appearance on Spain’s bilateral-agreement index does not prove that self-employed remote work is covered. UGE’s current public materials conflict here: the holder checklist recognizes an instrument-specific certificate and says it exempts Spanish registration, while the separate UGE FAQ says bilateral import is unavailable to self-employed workers. Do not select the branch without written, case-specific confirmation from the competent origin institution and UGE.
-
Is there no applicable international route or matching certificate? Plan the Spanish domestic branch: professional-basis evidence for UGE, Form 036 before activity where required, a RETA commitment in the UGE file, and RETA registration once authorization is obtained and before activity.
How the UGE filing should be described
The legal event is a communication/modification of conditions, not an ordinary renewal. UGE’s current checklist is titled “initial applications” but expressly includes existing authorization holders who report a modification during validity. The MI-T form also places a current Spanish residence holder within its initial route. Read together, the safest description is: a modification/communication handled through the current initial-application materials (UGE holder checklist).
This wording matters. The heading does not prove that every holder receives a guaranteed new permit or a restarted validity period. Timely communication is necessary, but UGE still assesses whether the new professional facts meet the law. Confirm the current electronic-office option and form marking before submission. UGE states that applications, communications and related documents are submitted electronically (UGE submissions page).
The public materials also leave one practical point unresolved. The law states a three-month prior commercial-relationship requirement for a professional-basis application, while UGE says the three-month evidence is not re-required for certain existing-holder modifications and, in the same guidance, warns that old employment evidence cannot prove a professional relationship (Ley 14/2013, Article 74 ter; UGE holder checklist). Prove the real new professional relationship, and obtain written UGE confirmation on whether completed professional-history months are required in your exact transition.
Build a bounded evidence pack
This is a transition pack, not a universal application checklist. Organize documents by the decision they support:
- Identity and current status: the authorization and resolution, proof that it remains in force, and a legible copy of the complete valid passport—all pages—as requested by the current UGE checklist.
- The actual change: employment termination or amendment, the effective change date, and a short chronology separating the end of employment, formation of the professional relationship and start of activity.
- Professional basis: signed commercial contract or contracts with non-Spanish companies, professional terms, remote-delivery evidence, scope, expected period and proof that the relationship is genuine rather than employment relabelled as contracting.
- Foreign enterprise and capability: official registry or equivalent evidence that the foreign enterprise has carried on real, continuous activity for at least one year, plus a recognized higher-education, vocational-training or business-school credential, or at least three years of documented analogous professional experience relevant to the work (Ley 14/2013, Articles 74 bis–ter). UGE may request more where the submitted proof is insufficient.
- Social security: old A1, the changed facts sent to the issuer, physical work locations, any prior self-employed history needed for the claimed route, and the resulting current certificate or Spanish-legislation determination. If foreign coverage is claimed, UGE asks for a certificate that expressly covers remote work from Spain; a mere application is not enough (UGE holder checklist).
- Spanish registrations: filed Form 036 and RETA evidence if activity has already begun and those registrations apply; otherwise, documents showing the planned compliant sequence.
- Continuing conditions: current evidence of resources, coverage and any other admission condition affected by the change. Add family-link documents only if a family filing or family-condition change is actually involved. Any family application or modification is separate; no matching duration or outcome follows automatically from the holder’s decision.
The 20% Spanish professional-activity rule
A professional-basis holder may work for a company in Spain only when that work is no more than 20% of total professional activity. UGE adds that the qualifying foreign professional relationship must continue and the Spanish relationship must remain professional, never employment (Ley 14/2013, Article 74 bis; UGE FAQ).
Do not invent the denominator. The cited law and UGE FAQ do not define whether “total professional activity” is measured by revenue, hours, days, invoices, clients or another measure, or over which period. Before accepting Spanish clients, obtain a written calculation approach for your facts and keep consistent records supporting it. The rule does not permit Spanish employment up to 20%.
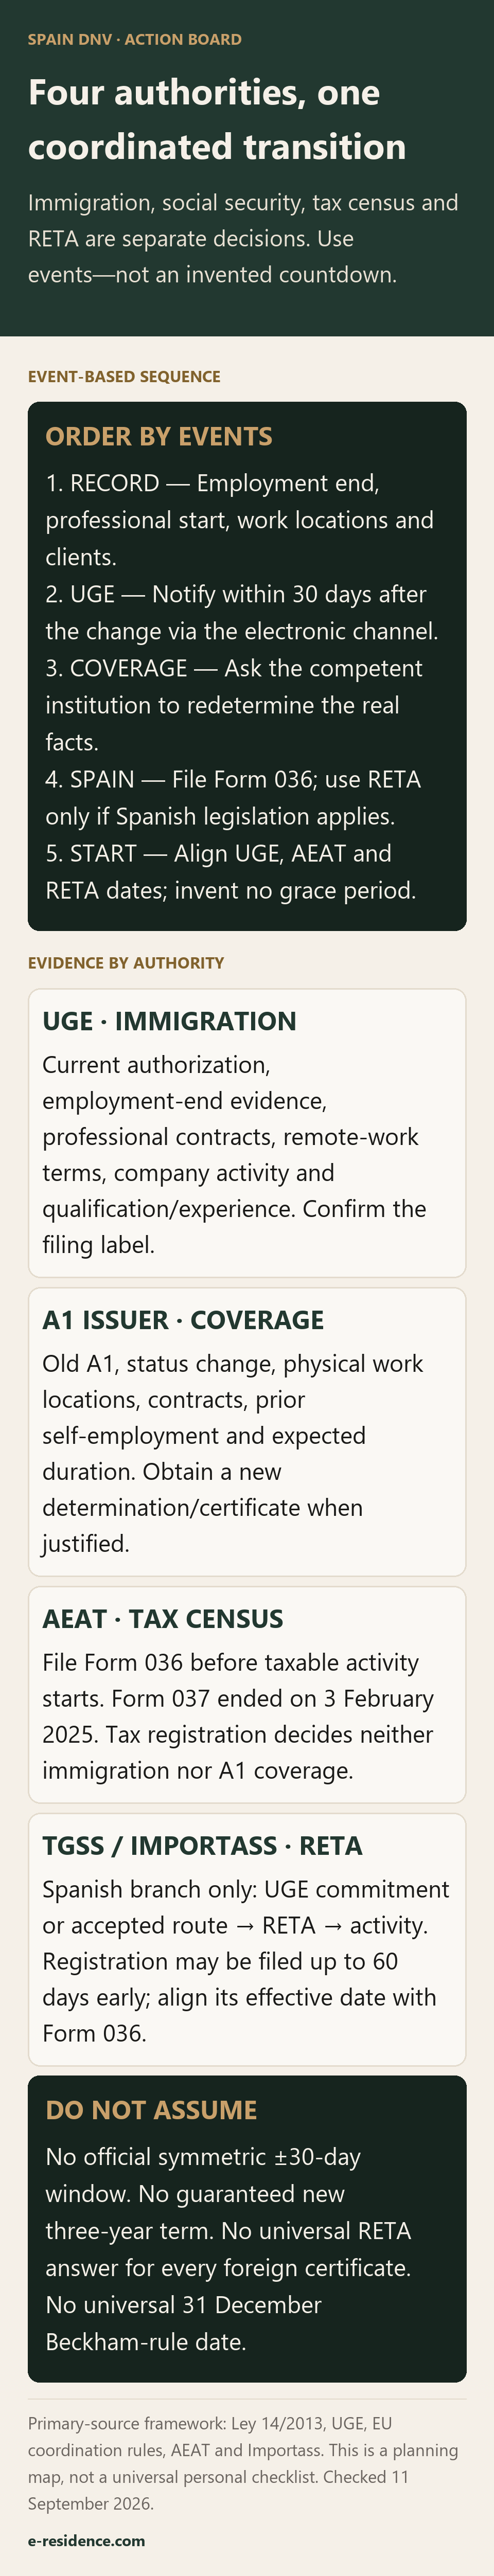
Event-based timing planner
| Event | Action tied to that event |
|---|---|
| Authorization review and expiry | Check the authorization’s legal expiry date; do not assume the modification changes it. |
| Employment ends or materially changes | Record the effective date, notify the A1 issuer and retain cessation evidence. |
| Professional relationship forms | Record the contract date, effective date, counterparties and remote-work terms; prepare the UGE evidence. |
| A1 facts cease to describe reality | Request a new applicable-legislation determination; do not use the employee A1 as proof of self-employment. |
| Before activity or operations begin | File Form 036 where required and register in RETA if Spain applies; when both AEAT and RETA are required, their effective dates should coincide (Importass guide). |
| Authorization conditions change | Communicate the change to UGE within 30 days after the actual event through the current electronic route. |
| UGE issues a decision or instruction | Record its scope, conditions and date; adjust the planned sequence without assuming a new validity period. |
| After filing and starting | Keep receipts, decisions, contracts, invoices and records of continuing foreign professional activity and any Spanish-client percentage. |
If the change has already occurred, do not manufacture a new date. Document the true chronology, file the UGE communication within the remaining statutory period if possible, and address any AEAT or RETA filing that was already required.
Common mistakes
- Treating the A1 as immigration permission or tax registration.
- Saying the old A1 automatically became invalid, instead of reporting changed facts and obtaining redetermination.
- Assuming the old employee A1 proves a new self-employed pattern.
- Calling the UGE step an ordinary renewal or promising a fresh validity period.
- Relabelling employment as self-employment without changing the real working relationship.
- Starting activity before Form 036 and any required RETA are effective, or without first confirming how UGE wants the condition change routed and evidenced.
- Using obsolete Form 037 instead of the current Form 036 route.
- Applying the EU multi-state rule merely because a client or employer is foreign.
- Treating a country’s agreement with Spain as proof that the treaty covers self-employed remote work.
- Calculating the Spanish-client ceiling with an unsupported denominator.
- Assuming a long or indefinite client contract guarantees any authorization term.
- Treating the Beckham regime as a side note. If you use Spain’s special inbound-worker tax regime, stop and obtain tax advice before changing the activity; do not infer either continuation or exclusion from DNV status alone (AEAT overview).
For the ordinary Spanish registration process after the route is settled, see how to register as autónomo in Spain.
Frequently asked questions
Does my employee A1 remain valid after I become self-employed?
Do not treat it as proof of the new facts. It is not automatically invalid merely because circumstances change, but the employee basis no longer describes genuine self-employment. Notify the issuer and obtain a new applicable-legislation decision; the issuer decides whether the old document must be withdrawn or replaced.
Is this a DNV renewal or a change of conditions?
It is a modification/communication of conditions, handled through UGE’s current materials titled for initial applications. It is not an ordinary renewal, and the filing route does not itself guarantee a new authorization or change the current expiry date.
Do I have 30 days before and after the change?
No. The statutory rule is to communicate a change affecting the authorization conditions to UGE within 30 days after it occurs. There is no official symmetric 30-day-before/30-day-after window.
Can I start invoicing before the UGE, AEAT and RETA steps are complete?
Do not assume so. In the Spanish branch, include a RETA commitment in the UGE file; once authorization is obtained, register in RETA before activity. Form 036, where required, must also be effective before the business activity or operations begin. The UGE communication duty retains its own 30-day period after the change affecting the authorization conditions. If you have already started, disclose the true date and correct any overdue step promptly.
Can I keep an employee job and freelance at the same time?
Not without case-specific confirmation. EU social-security rules can cover some mixed or multi-state patterns, but the DNV materials describe employment and professional activity as distinct scenarios and do not clearly authorize every hybrid under an unchanged file. Ask UGE and the competent social-security institution to decide from the real physical work pattern.
Can self-employed DNV holders work with Spanish clients?
Yes, but only as professional activity, while maintaining the qualifying foreign professional relationship, and only up to 20% of total professional activity. The cited law and UGE FAQ do not define the denominator or measurement period, so obtain and document a case-specific method before taking Spanish work.
Does an indefinite client contract guarantee a three-year permit?
No. The law describes the residence authorization as valid for the requested period up to a maximum of three years; an indefinite contract does not guarantee that term (Ley 14/2013, Article 74 quinquies). A mid-permit modification also does not automatically restart the validity period.
Does changing to autónomo automatically end the Beckham regime?
Do not assume either result. The tax regime has its own conditions, separate from UGE, A1, AEAT census registration and RETA. Stop and obtain advice on the proposed activity before making the change.
Next step
Once the immigration and social-security route is confirmed, you can register as autónomo online. The registration service is the implementation step; it does not replace the UGE or applicable-legislation decision.